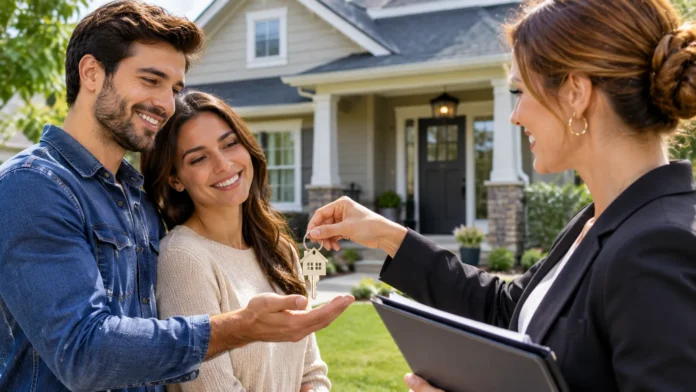

Buying a house is one of the biggest financial decisions many people make in their lifetime. It can be an exciting experience, but the process may also feel confusing when you are purchasing property for the first time. From understanding mortgage options to choosing the right neighborhood, several important decisions can influence your financial future and overall satisfaction.
Learning how to buy a house can help you avoid common mistakes, understand homeownership costs, and make informed decisions throughout the process. Whether you are looking for a starter home, a family property, or a long-term residence, careful planning is essential. Understanding each step can make buying your first home less stressful and more manageable.
Step 1: Determine If You Are Ready to Buy a House
Before beginning your home search, evaluate whether purchasing property matches your current financial situation and long-term plans. Homeownership involves more than making monthly mortgage payments. Property taxes, insurance, maintenance, and unexpected repairs can create additional expenses. Understanding these responsibilities helps you decide whether buying a home is appropriate for your circumstances.
Consider your employment stability, available savings, and existing financial commitments. A reliable income can help you manage regular housing expenses, while emergency savings provide protection against unexpected costs. However, there is no single financial situation that guarantees readiness. Your decision should reflect your responsibilities, financial flexibility, and comfort with a long-term commitment.
Think about how long you expect to live in the property and whether your future needs may change. Buying a house usually involves transaction costs that can make short-term ownership expensive. If you anticipate relocating soon, renting may provide greater flexibility. Reviewing your personal goals before purchasing helps prevent rushed decisions and unnecessary financial pressure.
Step 2: Set a Realistic Home-Buying Budget
Creating a realistic budget is one of the most important steps in learning how to buy a house. Begin by reviewing your monthly income, regular expenses, debts, and savings. Determine how much you can comfortably allocate toward housing without neglecting essential responsibilities. Your budget should support financial stability rather than simply reflect the maximum amount a lender might approve.
Monthly homeownership expenses can include mortgage principal, interest, property taxes, homeowners insurance, and applicable association fees. Maintenance and repairs should also be considered when estimating affordability. A property with an attractive purchase price may still create significant ongoing expenses. Reviewing the total cost of ownership helps you compare different homes more accurately.
Use a mortgage calculator to explore how loan amounts, interest rates, and repayment periods influence monthly payments. However, calculations are estimates rather than guaranteed lending terms. Leave room in your budget for emergency expenses and future financial changes. A comfortable housing payment is generally more sustainable than stretching your finances to purchase a more expensive property.
Step 3: Check Your Credit Score and Financial History
Your credit history can influence mortgage eligibility, available loan terms, and borrowing costs. Mortgage lenders commonly review credit reports to understand how applicants have managed previous financial obligations. A stronger credit profile may improve access to competitive financing options. However, lenders also evaluate income, existing debts, and other financial information.
Before applying for a mortgage, review your credit reports for inaccurate information or unfamiliar accounts. Correcting errors may help ensure that lenders evaluate reliable information. Paying bills on time and managing existing obligations can also support your financial profile. Credit improvement usually requires consistent habits rather than a single quick adjustment.
Avoid making major financial commitments without considering how they could affect your mortgage application. Opening new credit accounts or taking on additional debt may change your borrowing profile. Requirements differ by lender and loan program, so professional guidance may be useful. Understanding your financial position early can help prevent complications during the home-buying process.
Step 4: Save for a Down Payment and Closing Costs
A down payment is the amount of money you contribute toward purchasing a property before mortgage financing covers the remaining eligible cost. The required amount depends on the loan program, lender, and property. Some mortgage options allow relatively small down payments. Others require more substantial savings based on borrower qualifications and lending conditions.
In the United States, certain conventional loans may allow down payments as low as 3% for qualifying borrowers. Some government-backed programs have different requirements, while eligible buyers may qualify for zero-down-payment options. A 20% down payment is not universally required. However, smaller down payments may involve mortgage insurance or other additional borrowing costs.
Closing costs are another important expense that first-time buyers sometimes underestimate. These may include appraisal charges, title-related expenses, lender fees, and other transaction costs. Buyers should also budget for moving expenses and initial household needs. Saving beyond the down payment helps create a financial cushion during the transition into homeownership.
Step 5: Understand Different Mortgage Loan Options
A mortgage is a loan used to finance the purchase of a property, with the home generally serving as collateral. Different mortgage programs have varying eligibility rules, repayment conditions, and costs. Understanding these differences helps buyers select financing that matches their circumstances. Choosing a suitable mortgage can influence housing affordability for many years.
Conventional mortgages are widely used and may be available with fixed or adjustable interest rates. Government-backed programs, such as FHA, VA, and USDA loans in the United States, serve borrowers who meet specific eligibility requirements. These programs differ in down payments, property conditions, insurance arrangements, and other features. Not every borrower qualifies for every option.
A fixed-rate mortgage generally maintains the same interest rate throughout the agreed loan term. An adjustable-rate mortgage may change according to its contractual conditions after an initial period. Buyers should compare potential payment changes, total borrowing costs, and repayment flexibility. Understanding the full agreement is essential before accepting any long-term financing commitment.
Step 6: Get Preapproved for a Mortgage
Mortgage preapproval helps buyers understand the loan amount a lender may be willing to provide based on an initial financial assessment. Lenders typically review income, credit information, assets, and existing financial obligations. A preapproval letter can also demonstrate financial preparation when making an offer. However, it does not guarantee final mortgage approval.
Before requesting preapproval, organize commonly required documents such as identification, income records, bank statements, and relevant employment information. Self-employed applicants may need additional financial documentation. Requirements vary depending on the lender and mortgage product. Providing accurate information can help reduce delays and prevent misunderstandings during the financing process.
Compare different lenders rather than accepting the first available financing arrangement. Interest rates, lender fees, mortgage insurance, and other loan terms can affect the total cost. Review official loan estimates carefully and ask questions about unfamiliar charges. Comparing offers on similar terms helps buyers make informed decisions about long-term borrowing.
Step 7: Choose the Right Location and Neighborhood
Location is one of the most important factors when deciding which house to purchase. A property may offer attractive features, but its surrounding environment can affect daily convenience and long-term satisfaction. Consider commuting needs, transportation options, essential services, and neighborhood characteristics. Choosing a suitable location should reflect your lifestyle rather than popularity alone.
Research nearby schools if they are relevant to your household, along with healthcare facilities, shopping areas, and recreational spaces. Visit potential neighborhoods at different times when practical to understand traffic and general activity. Also investigate environmental risks, including flooding or other location-specific concerns. These details may influence property insurance costs and ongoing living expenses.
Think about future needs as well as immediate preferences. A location that works today may become less convenient if employment, family responsibilities, or transportation requirements change. However, predicting every future circumstance is impossible. Focus on practical priorities and gather reliable information before deciding which neighborhood best matches your expectations.
Step 8: Work With a Real Estate Agent
A real estate agent can help buyers search for properties, understand local market conditions, and navigate transaction procedures. Agents may provide information about comparable home sales, arrange viewings, and assist with negotiations. Their guidance can be particularly useful for first-time homebuyers unfamiliar with property transactions. However, buyers should understand the agent’s responsibilities and compensation arrangements.
When selecting an agent, consider relevant experience, communication style, and knowledge of your preferred area. Ask how they identify suitable properties and explain unfamiliar parts of the purchasing process. A professional should be willing to discuss risks and limitations rather than pressure you toward a quick decision. Clear communication can improve the overall buying experience.
Real estate representation rules and payment arrangements vary by location and agreement. In the United States, buyers may need to sign a written representation agreement before touring homes with an agent who works under applicable brokerage rules. Review compensation terms and contract obligations carefully. Consider qualified legal advice when you need help understanding important agreements.
Step 9: Search for Houses and Attend Property Viewings
Once your budget and preferred location are established, begin searching for properties that meet your essential requirements. Consider the number of bedrooms, bathrooms, living spaces, and other practical features. Separate necessary characteristics from optional preferences. This helps you compare homes without becoming distracted by attractive features that do not support your needs.
Online property listings can help you explore available homes and compare advertised prices. However, photographs and descriptions may not reveal every condition or limitation. Attending property viewings provides an opportunity to examine layouts, natural lighting, storage, and general maintenance. Visit more than one suitable property before making a major purchasing decision.
During viewings, look for signs of moisture problems, visible damage, unusual odors, and neglected maintenance. Ask questions about major systems and known property issues, while recognizing that sellers and agents may not know every defect. Avoid assuming that attractive renovations guarantee structural quality. A professional home inspection remains important even when a property appears well maintained.
Step 10: Make an Offer and Negotiate the Price
When you find a suitable property, the next step is preparing a purchase offer. An offer typically includes the proposed price, important deadlines, financing arrangements, and relevant conditions. Your real estate agent or qualified adviser can help explain customary terms. The goal is to submit an offer that reflects property value and your financial limits.
Research comparable property sales before deciding how much to propose. The asking price does not necessarily represent the home’s actual market value. Property condition, location, current demand, and available alternatives can influence negotiations. Avoid increasing your proposed price beyond your comfortable budget simply because you feel emotionally attached to a house.
Sellers may accept an offer, reject it, or propose different terms. Negotiations can involve price, closing dates, repairs, and other contractual conditions. Buyers should understand any contingencies involving financing, inspections, or appraisal results. These protections can affect the ability to withdraw from a transaction without losing money, depending on the agreement.
Step 11: Schedule a Professional Home Inspection
A home inspection helps buyers understand the visible condition of a property before completing the purchase. Qualified inspectors typically examine accessible structural components, roofing, plumbing, electrical systems, and other important features. Their findings may identify repairs or concerns requiring additional evaluation. An inspection provides valuable information but cannot guarantee that every problem will be discovered.
Review the inspection report carefully and ask questions about significant findings. Some problems may require assessment by specialized professionals, particularly when they involve structural damage, moisture, or major mechanical systems. Consider the potential repair costs and how they fit your budget. A house that appears affordable initially may require substantial additional spending.
Depending on the purchase agreement, inspection findings may allow buyers to request repairs, negotiate terms, or exercise an inspection contingency. However, these options depend on the contract and applicable local rules. Do not assume every discovered defect requires the seller to make repairs. Understanding your contractual rights helps prevent unexpected disagreements.
Step 12: Complete the Appraisal and Mortgage Process
A property appraisal provides an opinion of the home’s value based on relevant market information and appraisal methods. Mortgage lenders commonly require an appraisal to evaluate the property supporting the loan. The appraised value may differ from the agreed purchase price. This difference can influence financing requirements and the amount of cash needed at closing.
After an accepted offer, the lender continues reviewing financial documentation and property information. This stage may involve employment verification, updated statements, underwriting, and confirmation of loan conditions. Respond promptly to legitimate requests for additional information. Avoid major financial changes before closing unless you understand how they may affect approval.
A low appraisal or unexpected underwriting concern can delay or complicate the transaction. Possible solutions depend on the lender, purchase contract, and available finances. Buyers may need to reconsider terms or discuss alternatives with relevant professionals. Maintaining communication with the lender and real estate representatives helps address issues before the scheduled closing date.
Step 13: Review Closing Documents and Final Costs
Closing is the stage when the property transaction is completed according to the applicable legal and financial procedures. Before closing, buyers receive important documents explaining final loan terms, charges, and payment responsibilities. In qualifying United States mortgage transactions, lenders generally must provide the Closing Disclosure at least three business days before consummation, subject to applicable rules.
Review the final figures and compare them with earlier estimates. Pay attention to the interest rate, monthly payment, cash required to close, taxes, insurance, and other charges. Ask questions about unfamiliar fees or unexpected differences. Understanding these obligations before signing helps prevent unpleasant surprises after the property becomes yours.
A final walkthrough may allow buyers to check the property’s condition shortly before completion. Confirm that agreed repairs or other contractual requirements have been addressed when applicable. Closing procedures differ across jurisdictions, so follow the instructions of qualified professionals. Once the transaction is legally completed, ownership transfers according to the applicable process.
Step 14: Prepare for Moving Into Your New Home
After purchasing a house, the next step is organizing a practical move. Plan transportation, packing materials, utility arrangements, and important address changes before moving day. Keep essential documents and personal items accessible during the transition. A clear moving plan can reduce confusion and help you settle into your new property.
Before moving in, review essential home systems and identify important maintenance information. Locate electrical controls, water shutoff valves, and other relevant household features. Consider appropriate safety equipment and address urgent repairs identified during inspections. Understanding these practical details can help you respond more effectively to everyday household situations.
Homeownership also requires ongoing financial planning after the purchase is complete. Regular maintenance, insurance renewals, property taxes, and occasional repairs can create continuing expenses. Setting aside funds for future needs helps protect financial stability. Treating homeownership as a long-term responsibility makes it easier to maintain your property and manage unexpected costs.
Common Mistakes First-Time Homebuyers Should Avoid
One common mistake is shopping for houses before understanding financial affordability. Buyers may become interested in properties that exceed their comfortable spending limits. Another mistake is focusing only on the mortgage payment while ignoring taxes, insurance, and repairs. A complete housing budget helps reduce financial pressure after purchasing.
Skipping professional inspections or ignoring major property concerns can also create expensive problems. A beautifully presented house may contain hidden maintenance issues that are difficult to recognize during a viewing. Buyers should carefully review available disclosures and inspection findings. Avoid rushing through important evaluations simply because the housing market feels competitive.
Emotional decisions can also interfere with practical judgment. Becoming attached to a particular property may encourage buyers to overlook limitations or accept unfavorable terms. Compare alternatives and review each decision against your original priorities. A successful home purchase should meet both your personal needs and realistic financial expectations.
Conclusion
Learning how to buy a house begins with financial preparation, realistic budgeting, and understanding the home-buying process. Checking your credit, saving for upfront expenses, and comparing mortgage options can help establish a strong foundation. Choosing the right location and property is equally important for long-term satisfaction.
The purchasing process also involves making an offer, completing inspections, securing financing, and reviewing closing documents. Each step provides an opportunity to identify risks and make informed decisions. Working with qualified professionals can help you understand complicated legal or financial requirements. Careful evaluation is generally more valuable than rushing to complete a purchase.
Buying your first home should be approached as a long-term financial and personal commitment. Consider not only the purchase price but also the responsibilities that continue after moving in. With thoughtful preparation, clear priorities, and appropriate professional guidance, you can navigate the home-buying journey with greater confidence.
Frequently Asked Questions
What Is the First Step to Buying a House?
Start by reviewing your finances, including income, savings, debts, and credit history. Establish a realistic budget before exploring properties or applying for mortgage financing.
How Much Money Do You Need to Buy a House?
The required amount depends on the purchase price, loan program, down payment, and closing costs. Some qualifying mortgage programs allow low down payments, but buyers should also maintain savings for emergencies.
What Credit Score Do You Need to Buy a House?
Credit requirements vary by lender and mortgage program. Some loans accept lower credit scores than others, while stronger credit histories may improve available financing terms and borrowing costs.
How Long Does It Take to Buy a House?
The timeline varies depending on property availability, mortgage approval, inspections, and closing procedures. Some transactions finish relatively quickly, while others take several months because of financing or contractual delays.
Can You Buy a House Without a Real Estate Agent?
Yes, purchasing without an agent is possible in many locations. However, buyers remain responsible for understanding contracts, negotiations, inspections, and legal requirements, making qualified professional guidance particularly valuable.